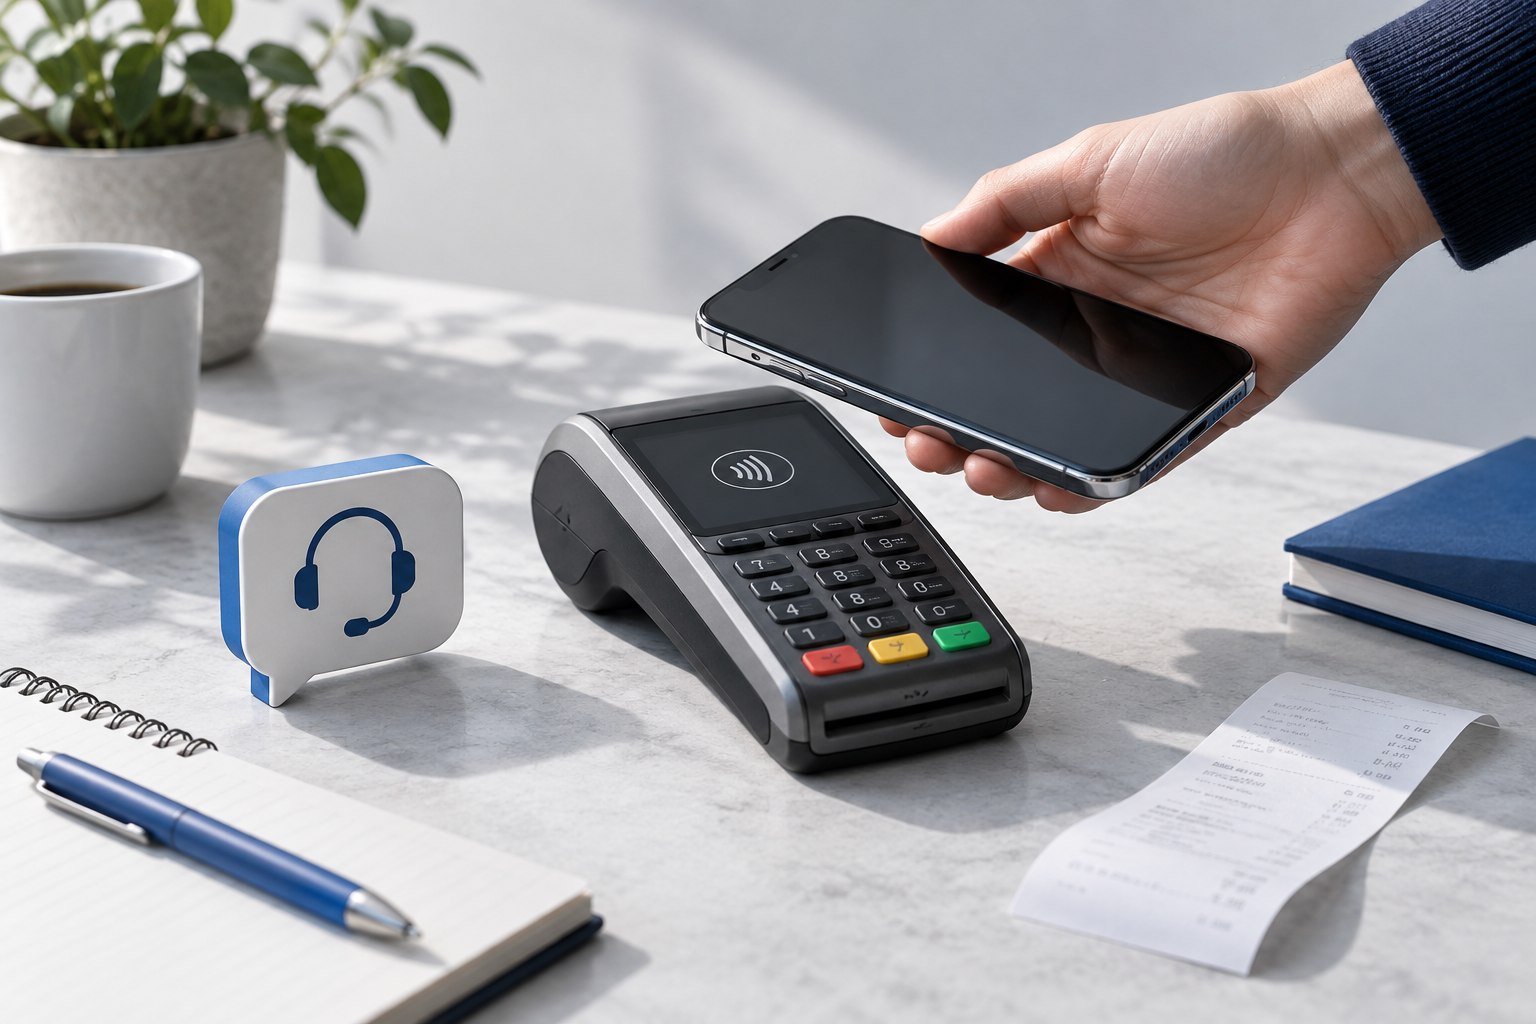
NPCI has announced UPI Tap & Pay on point-of-sale terminals and MyUPI, a customer-support platform powered by its FiMI small language model. RBI Governor Sanjay Malhotra unveiled the two capabilities at the Global Fintech Fest in Mumbai on 10 September.
The NPCI release describes a payment flow in which a user unlocks an NFC-enabled phone and taps an NFC-enabled POS terminal. The transaction can use the terminal’s internet connection, so it does not depend on the phone’s mobile internet connection.
That is a specific connectivity distinction. The announcement does not describe a transaction completed with no network connection anywhere in the payment chain.
What the tap flow supports
NPCI says the feature supports multiple UPI account types, including RuPay credit cards on UPI. Its release permits UPI PIN-less transactions up to ₹5,000; for higher amounts, it says users need to enter the UPI PIN on the POS terminal.
Those details belong to the newly announced POS flow. They should not be generalised into a claim that all UPI payments are now PIN-less or that any existing handset and merchant terminal can provide the experience.
The release builds on biometric authentication introduced at GFF 2025. It reports more than 6.29 billion biometric-authenticated UPI transactions as of 31 August 2026. That is a figure for biometric transactions, not adoption of the newly launched POS tap feature.
MyUPI brings support and controls together
NPCI describes MyUPI as a single view of UPI transactions and AutoPay mandates across banks and apps. Its announced features include beneficiary context, transaction replay and automated creation of chargebacks for eligible transactions.
A Safety Switch is intended to let users request that UPI debit transactions be declined when they suspect a compromise. Another control lets users delink their mobile number for receiving UPI payments.
Automated chargeback creation should not be read as a guarantee that every disputed payment will be refunded. The release limits the capability to eligible transactions and describes the creation of the process, rather than a universal outcome.
A launch with rollout questions still to check
NPCI says MyUPI will offer round-the-clock multilingual support. The release does not provide a complete bank-by-bank and app-by-app availability schedule for all the announced functions.
The changes address both making a payment and dealing with questions afterwards. At UPI’s reported annual scale, clear transaction records and support routes matter alongside the speed of the checkout. Actual availability still needs to be checked in the user’s supported app, bank and merchant setup.
Questions
Can the new POS tap flow work without the phone’s mobile internet?
NPCI says it can use the POS terminal’s internet connection. That does not mean the complete transaction is offline.
What PIN-less amount does NPCI specify?
The release states up to ₹5,000 for the announced flow; above that it says the UPI PIN is entered on the POS terminal.
Does automated chargeback creation guarantee a refund?
No. NPCI describes creation of chargebacks for eligible transactions, rather than a guaranteed result for every dispute.